
The market you launched in is not the market you’re operating in
Most operators preparing for a new market spend their energy on the wrong problem. The licence gets modelled, the tax gets budgeted, somebody builds a competitor map, the acquisition plan gets costed, and a business case running three years out goes to the board. It’s all sensible work, but it’s also built on a photograph of a market that will have moved by the time the brand goes live.
Here is how that usually plays out: the launch goes reasonably well. Traffic arrives, early numbers sit close enough to the model, and the team moves on to optimisation. Then somewhere around month five, something shifts. A payment provider might quietly withdraw from the vertical, or a verification standard that was guidance last year becomes a hard requirement this year. None of that is unusual – what happens next is where the money goes.
The operator raises it with their platform provider and is told it will be looked at. There is a roadmap. The request is understood, it has been logged, and there’s a release window in the second half of next year. Everybody is perfectly professional about it. Nothing gets fixed, and at Aloplay we have seen operators spend two quarters working around a gap in their own product.
The part nobody budgets for
Licensing gets attention because it comes with a deadline and an invoice, and at the end of it there is a certificate to point at. What follows has none of those qualities, which is why it rarely makes it into the business case.
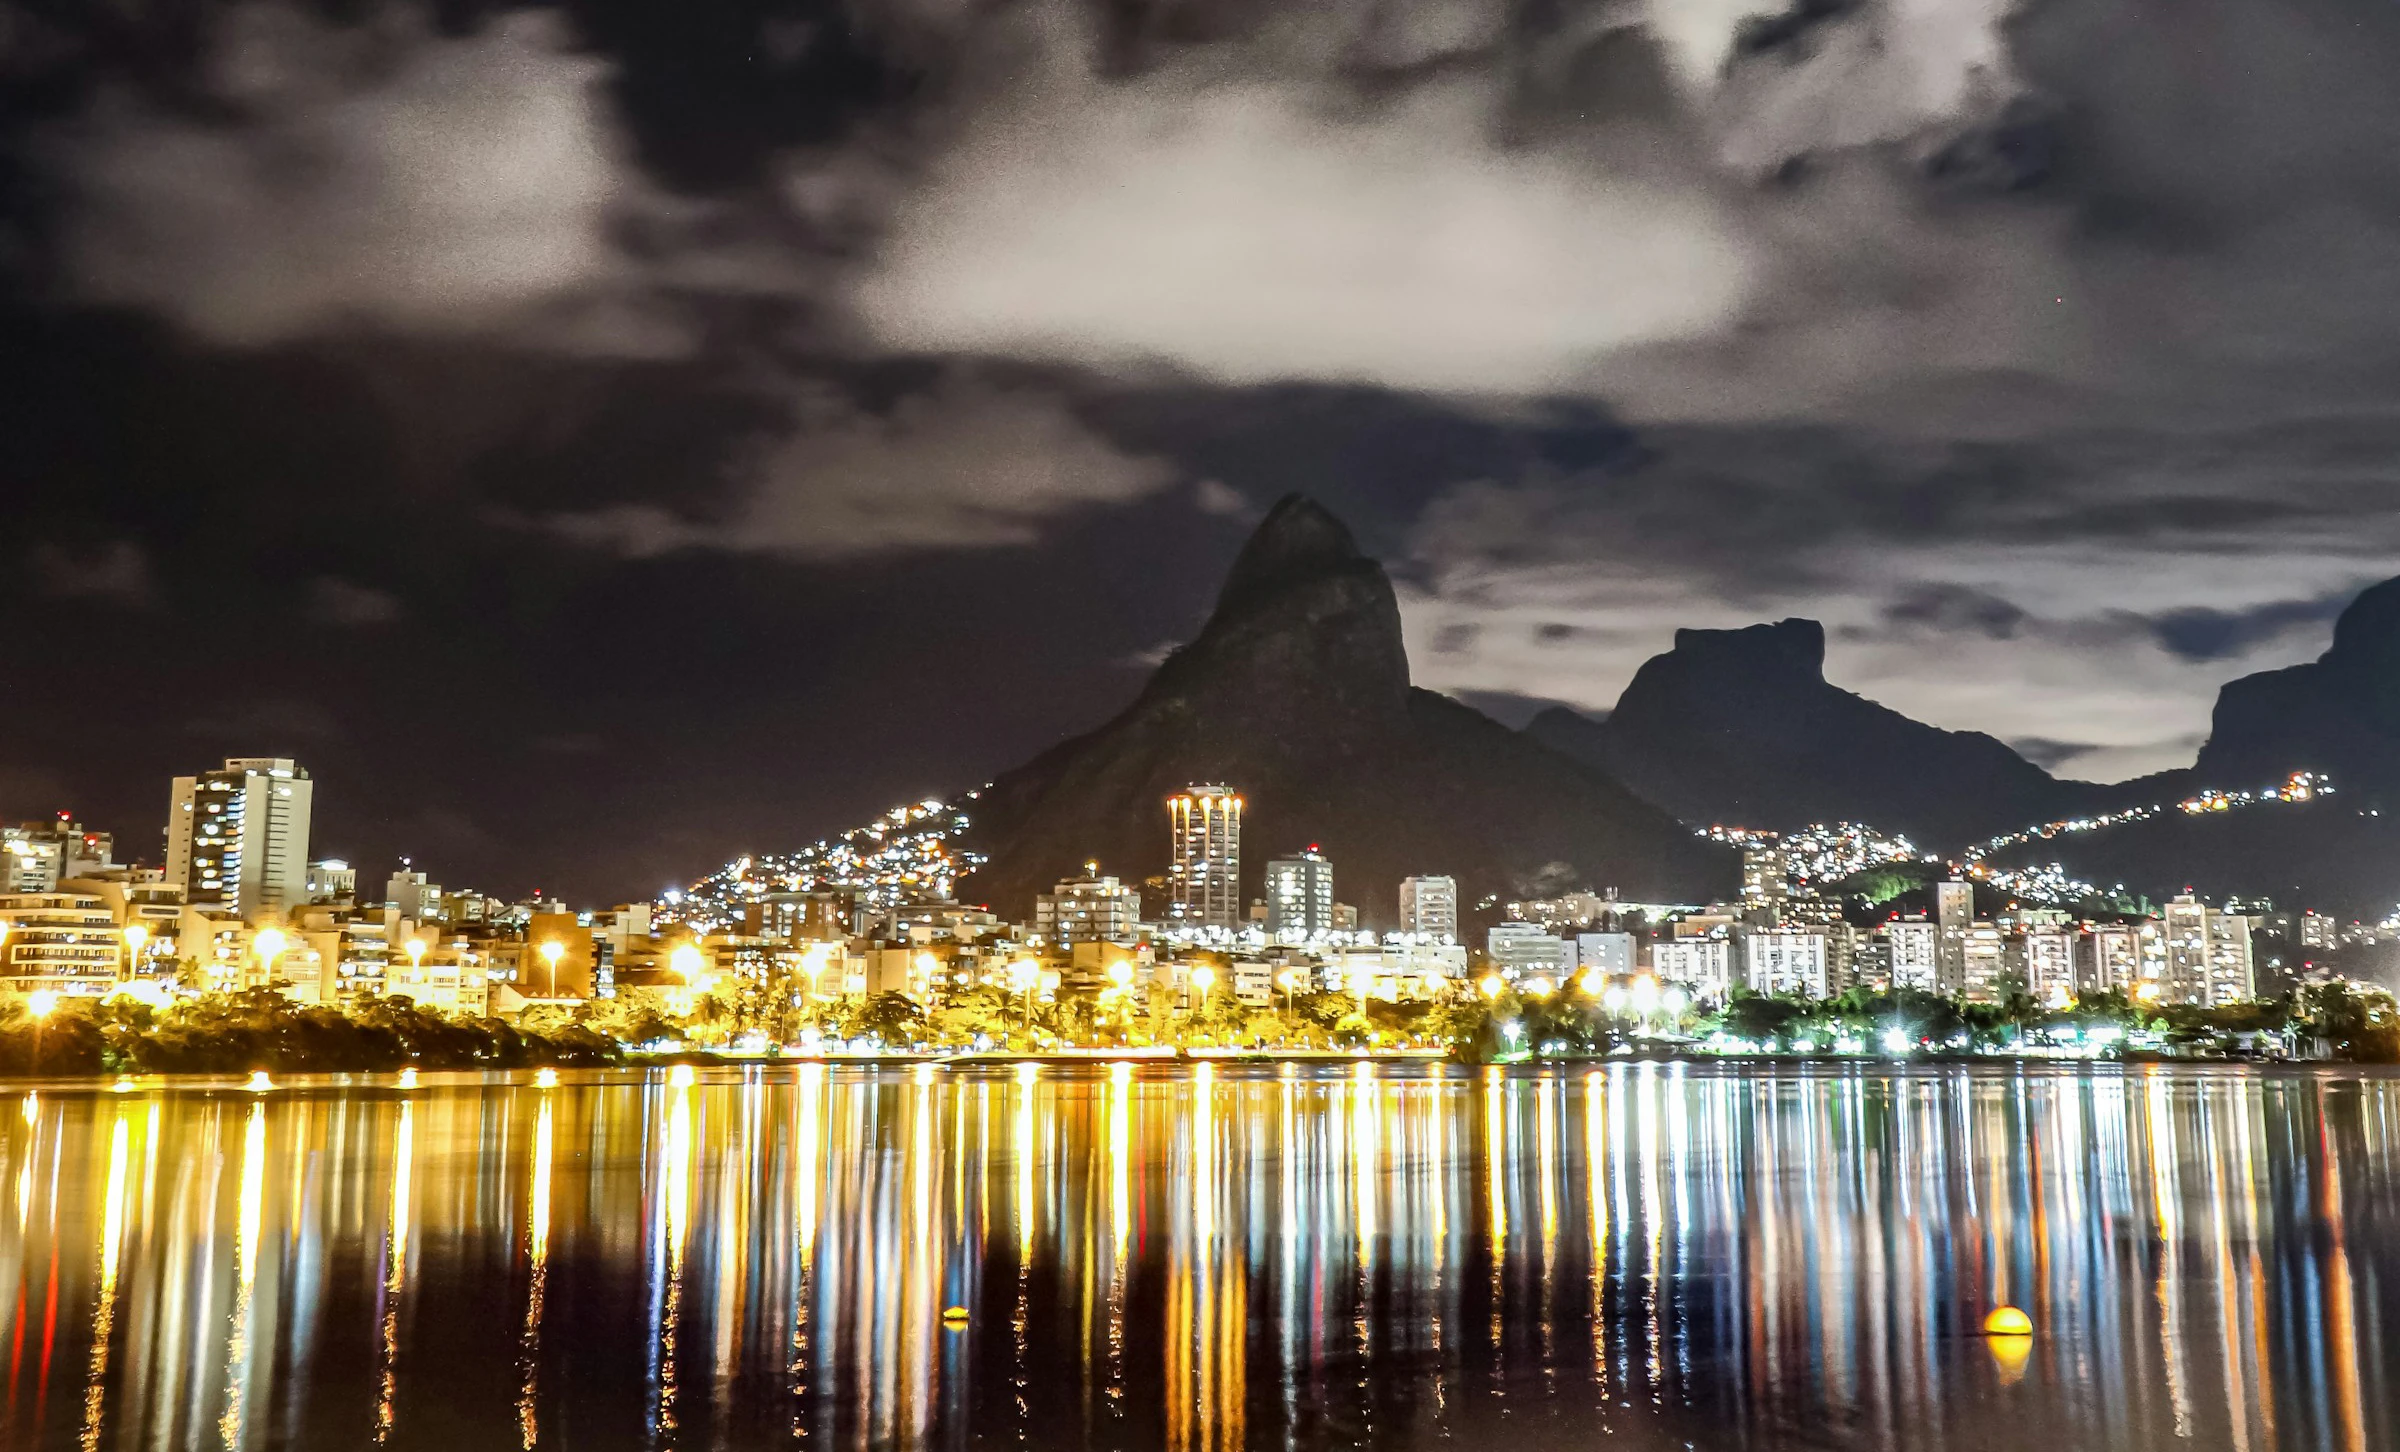
Look at Brazil, for example. Operators who came through the transition period are now working under a regulator that has moved from issuing guidance to issuing penalties, with identity verification expectations that have hardened considerably since those operators first modelled their entry. South Africa has produced its own version of the same story, where a court ruling redrew the line between what a bookmaker licence covers and what it does not, and a good number of businesses discovered their product roadmap had a problem in it.
Neither of those was a surprise to anyone paying attention. Both still caught operators out, because the platform underneath them could not move at the speed the market demanded. So the real question at the point of platform selection is not what the technology does today, but instead what happens the first time a market changes and you need something you didn’t know you’d need.
Localisation is not a translation project
Everybody understands the surface layer of localisation, such as getting the interface into the right language and weighting the lobby towards what local players actually play. The expensive part sits underneath.
Payments are the obvious example, and adding a local method is only the beginning of it. Players in different markets carry completely different expectations about how fast a withdrawal should be, and a delay that reads as normal in one country reads as a warning sign in another. Operators lose players over this constantly, and they usually diagnose it as a retention problem rather than a payments problem.
“A verification flow that works perfectly well in a mature European market can collapse when it meets a jurisdiction with heavier identity requirements.”
Onboarding behaves the same way. A verification flow that works perfectly well in a mature European market can collapse when it meets a jurisdiction with heavier identity requirements and lower tolerance for friction. The drop-off appears in the funnel long before anyone connects it to the compliance decision that caused it.
Then there is everything CRM touches. Bonus mechanics that drive reactivation in one market get ignored in another. Communication that feels attentive in Europe can feel intrusive in Latin America. Session lengths and preferred channels differ, and the definition of a valuable player differs enough that a lifted segmentation model will quietly mislead you for months.
Underneath all of it sits player behaviour, which is the one thing that genuinely does not travel. How somebody finds a brand, what makes them trust it, what brings them back – operators who treat that as a launch checklist tend to find out in their month-four retention numbers, by which point the acquisition budget has already gone.
When scale starts working against speed
If market requirements held still, scale would settle the argument. The provider with the deepest existing feature set would win every time, because whatever an operator needed would already exist somewhere in the stack.
Requirements do not hold still. They get revised across several jurisdictions at once, often with very little notice, and increasingly in response to political pressure rather than industry consultation.
Under those conditions, size starts working against you. A large provider carries deep capability, but it also carries a development queue, a change control process built for stability, and several hundred other clients with their own urgent requests. An operator who needs a payment integration inside six weeks is not helped by any of that. Their request is reasonable, but it’s also joining a long line.
Providers gaining ground in these markets have organised themselves differently – they treat a client’s market-specific requirement as something to build rather than something to log, and they have kept the distance between the operator and the person who can authorise the work extremely short.
That is a commercial choice far more than a technical one. It shows up in how fast somebody answers, whether the person answering can actually make a decision, and whether the relationship runs as vendor-and-client or as two businesses with the same problem.
Questions worth asking before you sign
Feature comparisons dominate platform selection, but they reveal surprisingly little about how a partnership will perform when the market changes.
Ask how long the last market-specific change took, start to finish. Ask who signs it off, and how many people sit between the operator and that person. Finally, ask what happened the last time a client needed something urgently that was not on the roadmap, and listen carefully to whether the answer describes a process or an outcome. The responses will tell you more about the next three years than any product demonstration.
Speed without a floor under it
None of this argues for picking the smallest provider on the exhibition floor. Agility that cannot handle a World Cup traffic spike has just relocated the problem, and an operator who trades roadmap delays for downtime hasn’t improved their position.
What emerging markets demand is harder to source than either quality by itself. Operators need a partner responsive enough to build inside their timelines, and stable enough that they never have to think about the platform during a peak. Plenty of providers claim both, but the actual number that can evidence both is considerably smaller, and it is worth making them evidence it.
It is exactly this balance that Aloplay has built its approach around: proven infrastructure combined with the ability to respond quickly as an operator’s market evolves.
The next decade of growth in this industry will come from markets that are still being written, across Latin America, across Africa, and in places that have not opened yet. The operators who do well in them will not necessarily be the best funded or the quickest to launch, but will be the ones whose platform partner could keep up when the market moved.