Why the world’s gaming leaders can’t afford to ignore changing sustainability regs
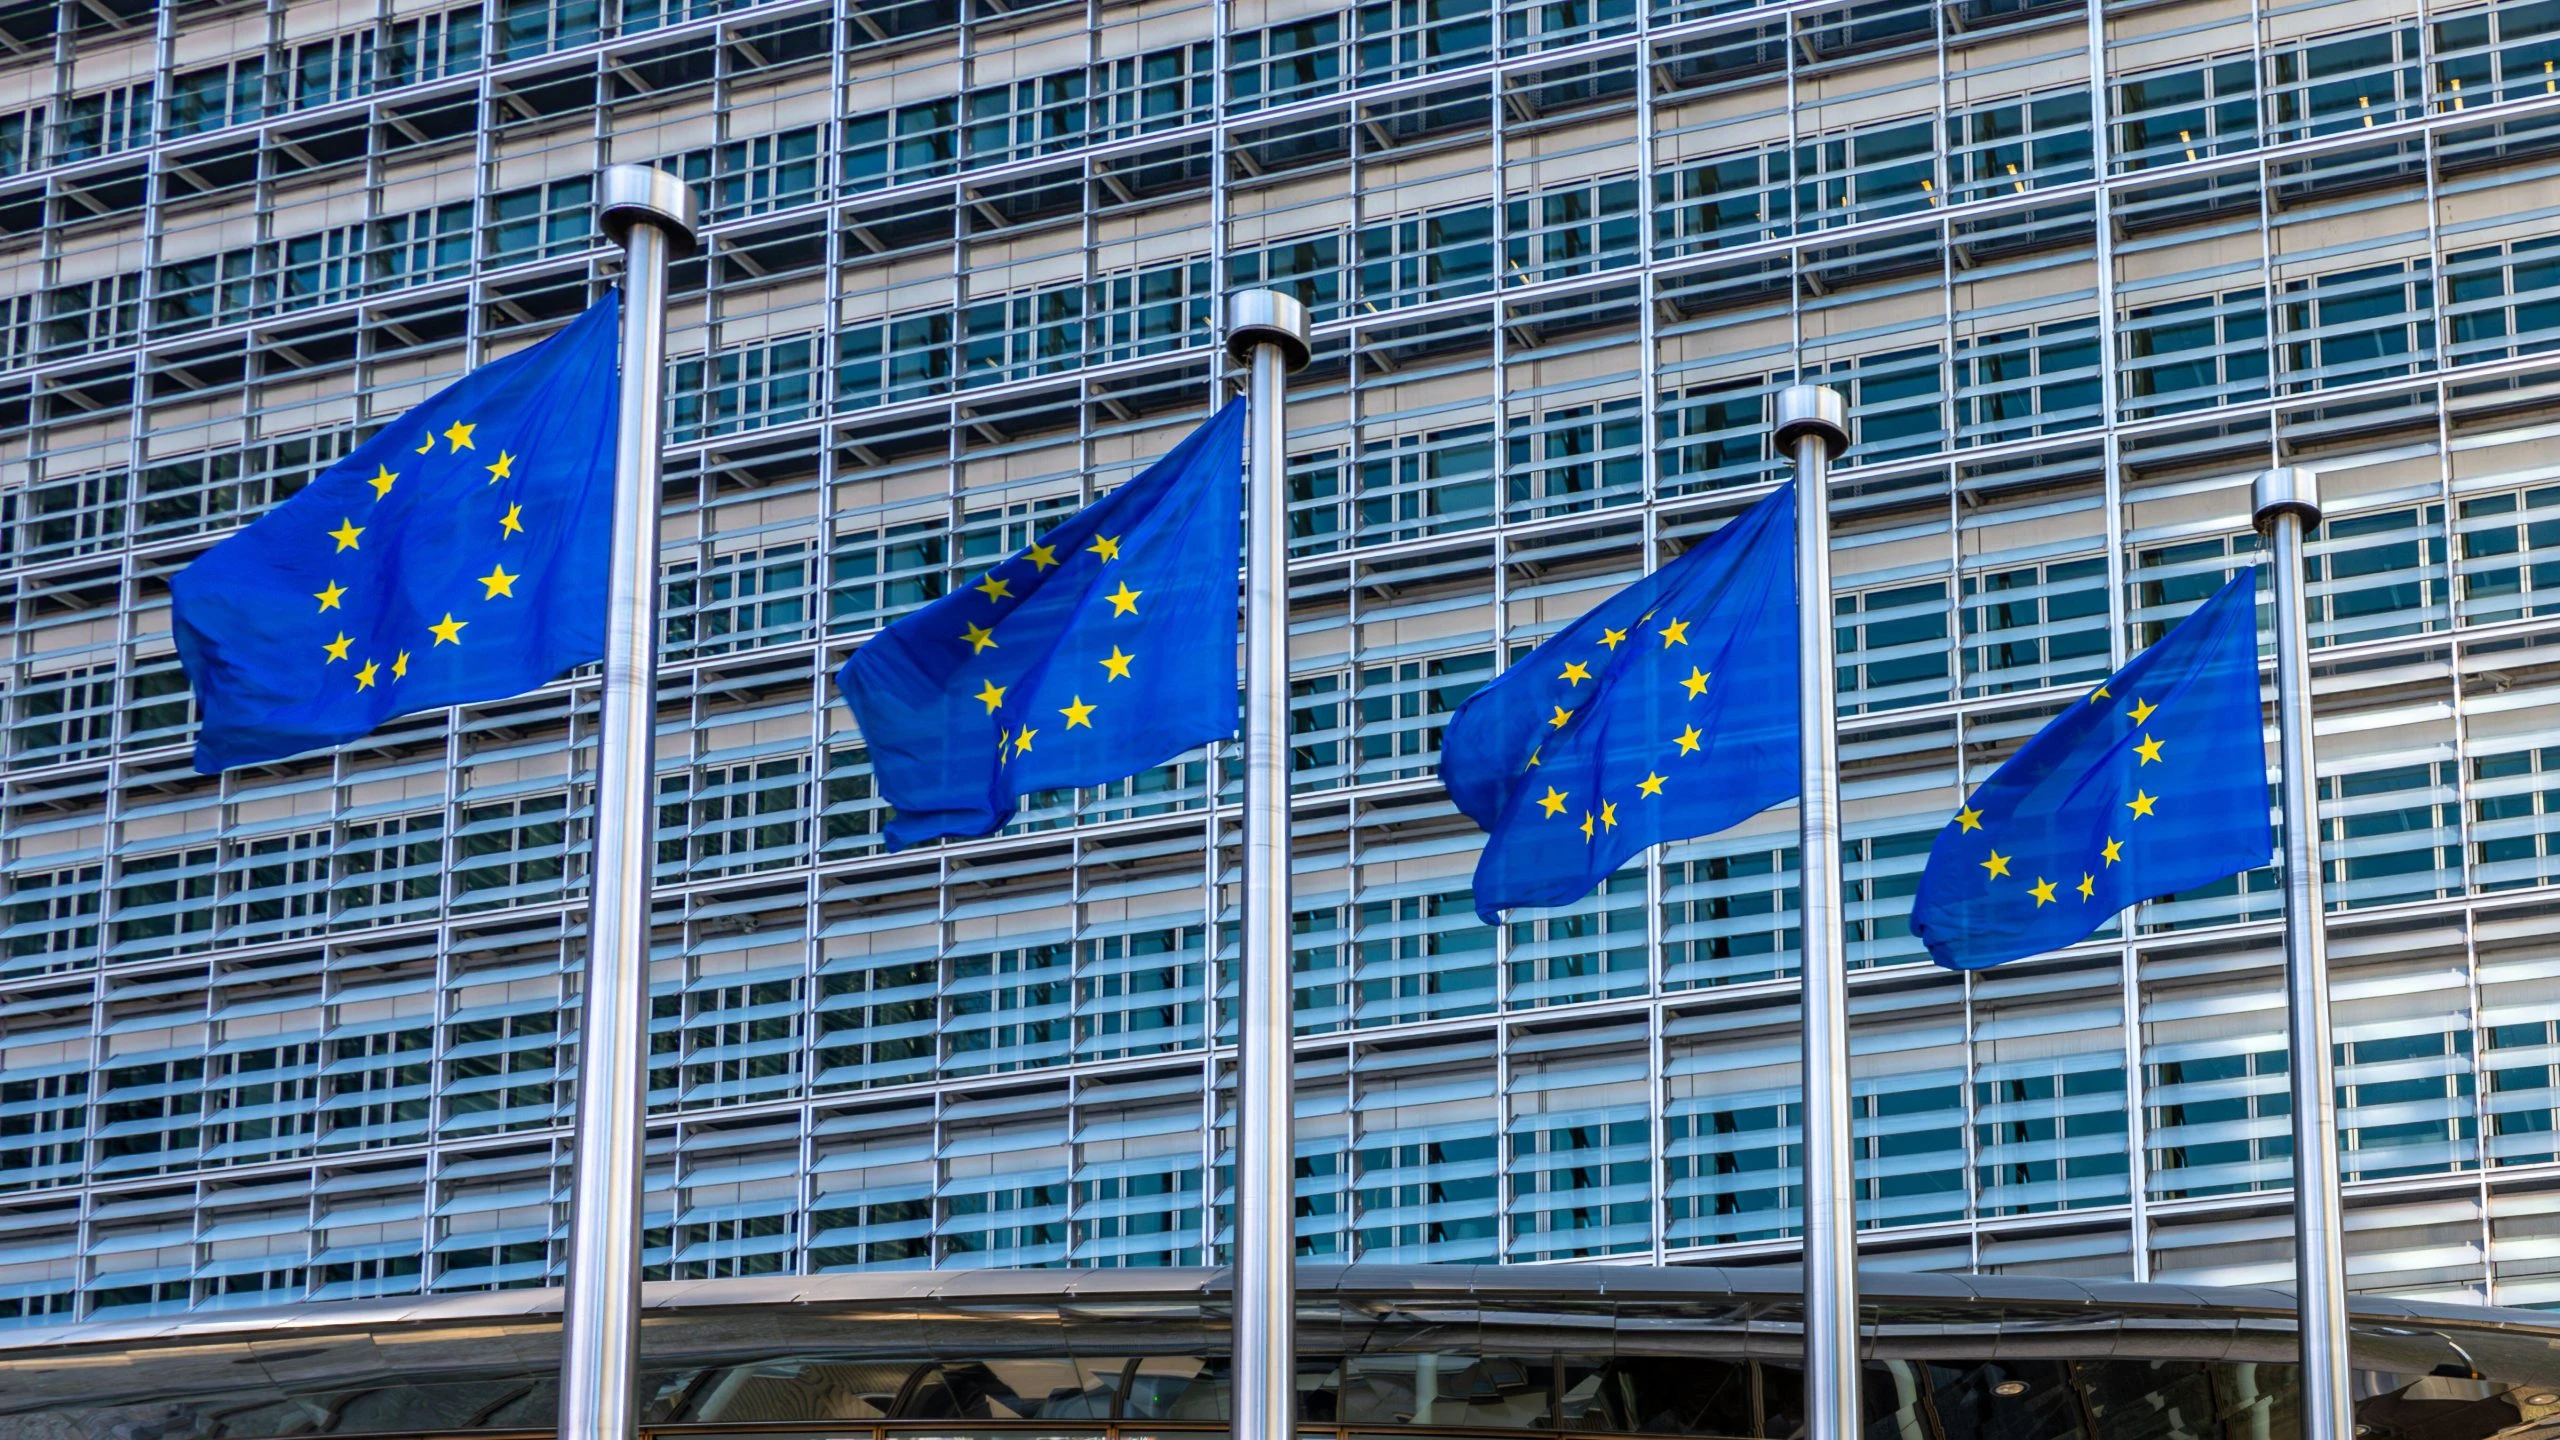
A structural shift is sweeping the global gaming industry. Driven by regulatory changes in Brussels, ripples are being felt across corporate boardrooms from London to Las Vegas and Macau. The European Union’s enacted ‘Omnibus Directive’ has reshaped the corporate reporting landscape by significantly narrowing the scope of the Corporate Sustainability Reporting Directive (CSRD).
Under this revised framework, the threshold for mandatory reporting has been raised substantially. Where the directive originally threatened to sweep up virtually every medium-sized enterprise operating within the internal market, the updated framework concentrates mandatory reporting on much larger entities, whether public or private. Specifically, the new thresholds target companies averaging at least 1,000 employees and generating upwards of €450 million in annual net turnover. Along with these higher financial and headcount thresholds, the EU has slashed the mandatory European Sustainability Reporting Standards data points by roughly 61%, an aggressive move intended to curb bureaucratic red tape and lower compliance costs while preserving European economic competitiveness.
For small and mid-market gaming businesses, this legislative pivot sparked a collective sigh of relief, sparing them from compliance budgets that threatened to drain core commercial resources. Yet, for the industry’s heavyweights – the large, publicly traded gaming giants spanning digital iGaming platforms, sprawling integrated casino resorts, and multi-jurisdictional technology manufacturing – the narrative is radically different.
For these tier-one operators and global suppliers, regulatory easing in Brussels does not equate to market relief. Whether a company operates iconic physical properties on the Las Vegas Strip, manufactures electronic gaming machines in Australia, or orchestrates high-volume digital sportsbooks across Europe, the financial stakes of sustainability reporting remain at an all-time high. Capital markets have matured. Institutional investors, tier-one debt underwriters, and sovereign wealth funds no longer view environmental, social, and governance (ESG) disclosures as discretionary public relations. Instead, they treat verified sustainability performance as a direct proxy for operational resilience, regulatory risk management, and long-term enterprise value. The simplification of the new reporting and creation of a level playing field should ensure a new-found consistency and also alleviate some of the existing greenwashing narrative.
The extraterritorial reach of the European rulebook
While the EU’s legislative adjustments were designed to alleviate administrative burdens on home-grown European enterprises, the CSRD remains an inescapable reality for the world’s largest gaming companies. Crucially, the directive possesses a formidable extraterritorial mechanism. Non-EU parent groups with significant operational footprints in Europe – specifically those generating substantial net turnover within the EU alongside a qualifying branch or subsidiary – fall squarely within the scope of the new regulations.
For the global gaming elite, avoiding this regulatory net is virtually impossible. Omnichannel juggernauts like Flutter Entertainment, Entain, and MGM Resorts International, alongside global equipment leaders like Aristocrat Leisure and Light & Wonder, cross the elevated size and revenue thresholds with ease.
Gaming companies based in North America or Asia are also inevitably swept into the reporting matrix via the global supply chain. In an increasingly interconnected B2B ecosystem, tier-one European operators facing CSRD obligations are legally required to audit their Scope 3 value-chain emissions and conduct human rights due diligence across their upstream suppliers. Consequently, any independent games studio, hardware manufacturer, or payments processor seeking commercial contracts with large, regulated operators must provide auditable, investor-grade ESG data or risk being excluded from procurement tender lists.
Parallel regulatory pressures are also accelerating globally. The International Sustainability Standards Board standards are gaining rapid statutory backing across jurisdictions including the UK, Australia and Canada. The inescapable truth for large-cap gaming is that sustainability transparency is no longer an isolated European policy experiment; it is the universal operating language of international commerce.
What is SustainabilityPlus?
The goal for large gaming companies is no longer just statutory compliance, but efficiently maintaining investor-grade transparency. This shift is evidenced by the rise of tailored platforms like Fintel Sustain’s SustainabilityPlus. By leveraging AI to analyse extensive public disclosures, regulatory filings, and audited operational reports, these platforms benchmark gaming companies against metrics that directly reflect realities. Focus is placed entirely on quantifiable tracking of responsible gaming interventions, monitoring of anti-money laundering controls, black-market displacement, and granular measurement of facility energy efficiency. By anchoring ratings in verifiable data, specialised platforms like SustainabilityPlus provide institutional investors and corporate boards with a reliable, common standard, eliminating the excessive administrative overhead historically associated with ESG reporting.
Omnichannel realities: From data-centre servers to casino floors
The regulated gaming industry has evolved into a global powerhouse generating upwards of half a trillion dollars in annual revenue. Yet, as the sector expands across both digital and retail channels, the operational footprint of gaming companies becomes increasingly intricate. Sustainability metrics must reflect the realities of distinct operating models across the entire value chain.
Land-based integrated resorts
For land-based casino operators, environmental and social dimensions are rooted in massive physical infrastructure. Integrated resorts demand round-the-clock power generation, complex HVAC systems, and intensive water usage. Proactive investments in on-site solar generation, water reclamation systems, and high-efficiency building retrofits yield immediate reductions in operating expenditures. On the social axis, these operators manage tens of thousands of employees, making labour relations, workforce diversity and community investments paramount to maintaining operational licenses.
Digital iGaming and sportsbooks
Digital-first operators present an entirely different operational profile. While their physical footprint is leaner, their digital infrastructure is vast. Cloud-server hosting and complex predictive analytics engines consume substantial amounts of energy, making data-centre carbon optimisation a critical metric. More critically, investors place extraordinary scrutiny on responsible gambling frameworks. Fund managers analyse how effectively an operator deploys artificial intelligence and real-time behavioural telemetry to identify markers of harm, mandate deposit limits, and intervene before problematic behaviour escalates.
B2B hardware and software suppliers
For suppliers, the emphasis turns towards circular product design, responsible component sourcing, and supply-chain logistics. Institutional capital favours manufacturers that design modular, upgradeable cabinets and champion closed-loop component recycling.
Across every vertical, the lesson is uniform: operational scale brings magnified public and institutional scrutiny.
The capital markets engine: Lower cost of capital
Why should the board of a publicly traded gaming enterprise allocate millions to sustainability initiatives when statutory obligations are being narrowed? The answer lies in corporate finance, balance-sheet optimisation and the cost of capital.
Historically, the gaming industry has carried a persistent valuation discount. Grouped loosely into the ‘sin stock’ category, gaming companies have frequently faced restricted pools of institutional capital. The persistent spectre of sudden regulatory crackdowns, license suspensions, and punitive fines means that investors inherently view opacity as unhedged risk. In financial theory, unhedged risk is penalised through a higher discount rate. But are gaming companies really at a higher risk than other sectors? The unified reporting will enable greater comparison industry to industry, and there may well be some surprises.
Today, capital providers systematically incorporate sustainability indicators into credit underwriting and equity valuation models. Lenders and debt investors, themselves subject to reporting mandates such as the EU’s Sustainable Finance Disclosure Regulation, face strict portfolio decarbonisation and social responsibility goals. When a gaming operator issues corporate bonds or refinances credit facilities, lenders heavily assess the borrower’s ESG maturity.
Operators showcasing verified reductions in carbon intensity, transparent governance frameworks, and peer-reviewed player-protection mechanisms are consistently rewarded with tighter credit spreads. On a large debt issuance, a spread reduction of just 25 to 50 basis points translates into millions of euros in annual interest savings. Over the life of a multi-year facility, those savings directly enhance free cash flow. Conversely, an operator that halts its reporting, citing the EU Omnibus threshold rollbacks, signals to credit committees that its risk-management controls are fragile, leading to wider spreads and restrictive covenants.
The equity markets paint an identical picture. Publicly traded gaming companies that achieve high ESG percentiles preserve their eligibility for broad-market indexes and active institutional portfolios, expanding liquidity and bolstering share prices. During M&A due diligence, target companies demonstrating clean, audited sustainability metrics avoid punitive valuation haircuts. As such, the new directive offers a real financial opportunity and incentive.
Rethinking ESG infrastructure and standardised data
If the financial benefits of sustainability are undeniable, gaming executives have historically pushed back against ESG frameworks primarily due to cost and structural inefficiency. For years, ESG data collection was an expensive, disjointed exercise. Gaming companies spent hundreds of thousands of dollars engaging disparate consulting firms and fielding bespoke questionnaires from generic rating agencies that fundamentally lacked the context to evaluate gaming enterprises.
The maturation of the market, combined with the shifting CSRD landscape, has spurred a transition away from bloated consulting models toward specialised, sector-specific data architectures. The European Commission’s adoption of the simplified voluntary standard provides smaller businesses and suppliers with a standardised, recognised format to respond to requests from tier-one clients without encountering excessive bureaucratic overhead.
The strategic divide: Regulated operators vs the black market
Beyond capital market dynamics, sustainability reporting has emerged as a frontline geopolitical asset for regulated gaming operators in their ongoing battle against unlicensed, black-market operations.
In every major jurisdiction, licensed operators face intense competition from unregulated offshore entities. These illicit platforms pay no local taxes, offer zero consumer safeguards, and ignore problem gambling indicators. Yet, in public discourse, anti-gambling critics frequently conflate the entire sector, painting legitimate, compliant operators with the broad brush of the rogue market.
Robust, verifiable sustainability reporting creates a clear, undeniable line of demarcation between the regulated industry and the grey market. When an operator can present audited, empirical data detailing its investments in responsible gaming technologies, tax revenues paid to municipal treasuries, and charitable contributions, it builds crucial political capital. This transparency is invaluable when securing operating concessions and license renewals, proving to regulators that an operator is a trustworthy, long-term civic partner.
Staying in the game
The European Union’s enacted Omnibus legislation marks a pragmatic recalibration of the continent’s regulatory machinery. The elevation of CSRD thresholds to 1,000 employees and €450 million in revenue is a significant legislative shift. But for the world’s largest gaming operators, the underlying reality has not changed.
In modern global finance, capital seeks certainty, transparency, and operational rigour. Because the gaming sector operates at the high-stakes intersection of consumer entertainment, sophisticated technology and intense regulatory oversight, it will always remain under the microscope.
Operators that embrace sustainability as a core financial discipline will continue to capture distinct advantages: lower borrowing costs, broader access to institutional equity, streamlined licensing, and resilient corporate valuations. In an industry defined by calculated risks and probabilities, long-term enterprise value belongs to those who master the changing sustainability rulebook.
Article Partner
SustainabilityPlus
SustainabilityPlus provides regulated gaming companies with an accurate, cost-effective way to get a sustainability rating.